Water in a basement can look like one problem. To an insurance company, it may be several different problems depending on where the water came from and how it entered the house.
A pipe that breaks inside the home is different from a sewer or drain backup. A sump pump that cannot keep up may raise another question. Water that moves across the ground and enters from outside can fall under the definition of flood. The cleanup may look the same, but the policy may not treat these events the same way.
That is why “I have water coverage” is not a very useful answer. A better place to start is: What caused the water, how does my policy define it, and what limit or deductible applies?
No article can tell you how a future claim will be decided. That depends on the policy, its endorsements and exclusions, the facts of the loss, and the carrier’s claim review. What this article can do is help you ask the right questions while the basement is still dry.
Why are sump overflow, water backup, and flood different questions?
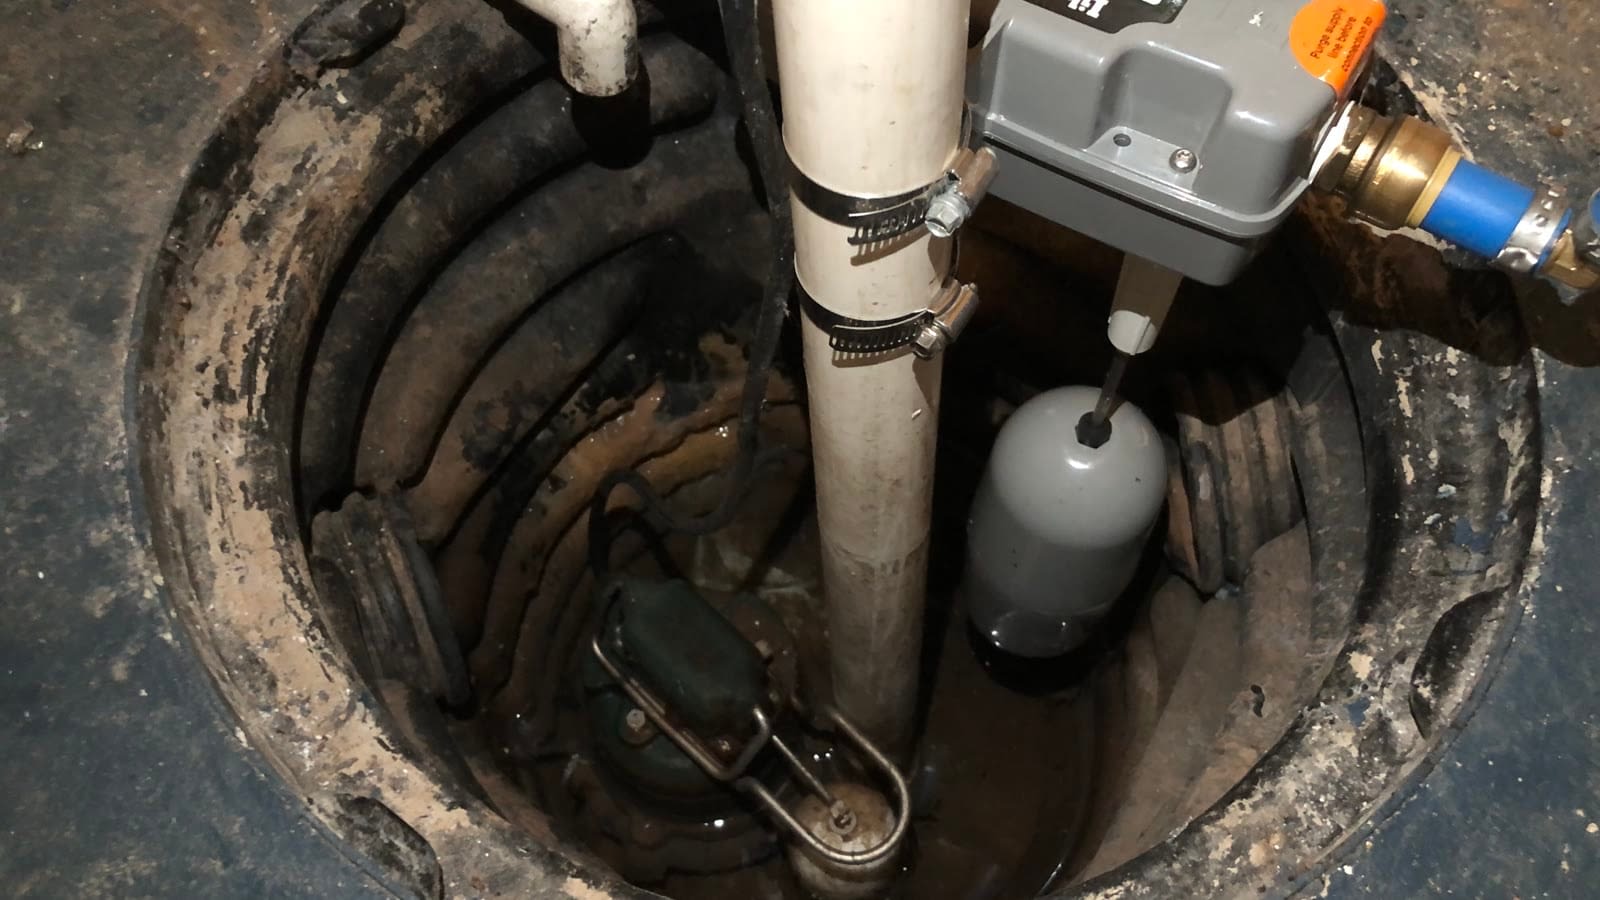
Most homeowners use “flooded basement” to describe any basement with water in it. Insurance policies are more specific. Water released by plumbing inside the house may be handled one way. Water coming back through a sewer or drain may be handled another way. A sump basin that fills faster than the pump can move water can create its own coverage issue. Outside water moving across normally dry ground may point to flood insurance instead.
The National Association of Insurance Commissioners’ homeowners insurance overview lists sewer or drain backup and flood as separate coverage questions. That is a good reminder to slow down and read the actual policy instead of relying on a coverage label.
The endorsement matters too. It may have a separate limit, deductible, or exclusion that is easy to miss if you only look at the declarations page.

What does Derek’s sump-pump story show?
I once reviewed a homeowners policy that showed water and drain backup coverage. The homeowner later had a sump pump overflow that damaged the basement and expected that coverage to apply. It did not. The policy language did not treat the sump pump overflow the way the homeowner thought it would.
That does not mean every water-backup endorsement works the same way. They do not. The point is that two policies can use a similar coverage name while the wording, exclusions, or limits produce a very different result.
A proper homeowners insurance review should begin with the house, not the old declarations page. Do you have a basement? Is it finished? Is there a sump pump? Have there been drainage problems before? Those details help determine which parts of the policy deserve a closer look.
What should you check before there is water?
Walk through the lowest level of the home while it is dry. Find the sump basin, floor drains, sewer cleanout, plumbing lines, water heater, and appliances that use water. Then look outside. Notice where downspouts discharge, how the ground slopes, and where water collects after a hard rain. An insurance review will not replace a plumber or drainage contractor, but these details help explain the risk.
Bring this information to the review:
- Where water could come from and how it could enter the home.
- What is below grade, including finished rooms, utilities, and personal property.
- Whether the pump has a battery backup, alarm, or recent maintenance.
- The current homeowners policy, water-related endorsements, limits, and deductibles.
None of this guarantees that a carrier will offer a particular endorsement or pay a future claim. It gives the agent enough information to show you the wording that matters and explain what you are buying.

When should flood insurance be part of the conversation?
Do not assume that a homeowners policy or water-backup endorsement replaces flood insurance. The NAIC discusses flood insurance separately, and federal NFIP guidance explains what a flood policy can cover, subject to that policy’s terms.
“Flood” also has a specific meaning in an insurance contract. A wet basement after heavy rain does not answer the question by itself. You still need to know where the water came from, how it entered, and how the policy defines the event.
If your property has a low point, nearby creek, drainage channel, steep slope, or a history of outside water, ask for a separate flood insurance review. Being outside a lender’s high-risk flood zone does not mean the risk is zero. The mortgage requirement should not be the only question you ask.
What should you ask the agency to show you?
Ask for the exact policy form or endorsement that addresses sewer backup, drain backup, and sump overflow. Have the agent show you whether those events are handled together or separately. Confirm the limit, deductible, and which damaged property may be included.
Then ask what is not covered by that wording. Does the homeowners policy exclude outside rising water? Is a separate flood policy the available option? Would a water-backup sublimit run out quickly if the basement is finished? These are the questions to settle before a loss, even though no one can promise how a future claim will be handled.
Keep the answer with your policy. Review it again if you change carriers, finish the basement, install a new sump system, or see a new endorsement at renewal. Our guide to homeowners risks that are easy to miss covers other parts of the policy that deserve the same attention.
Basement water insurance questions
Does water-backup coverage always include sump pump overflow?
No. Do not assume the name of the coverage answers the question. Read the endorsement and ask the agency to show you the wording for both sewer or drain backup and sump overflow.
Does homeowners insurance cover every kind of basement water damage?
No single answer fits every water loss. A broken pipe, sewer backup, sump overflow, seepage, and outside floodwater can be treated differently. The cause of the water and the policy language both matter.
Should I consider flood insurance if my lender does not require it?
It is still worth discussing. A lender requirement is based on its rules and the property’s mapped flood zone. It is not a complete review of how outside water could reach your home.
If you have a basement, sump pump, or drainage concern, request a strategy call with Derek Wiley Agency. We will start with the house, walk through the water exposures, and show you which policy questions need a clear answer.
Featured photo by Famartin, licensed under CC BY-SA 4.0 via Wikimedia Commons.